Invoice finance allows you to access cash based on the value of your unpaid invoices.
Rather than waiting days or weeks for your invoices to be paid by customers, an invoice finance facility means that lenders will advance you most of the value of the invoice immediately. This can be a helpful way for businesses to improve their cash flow and have access to the working capital they need to grow and succeed.
Organisation X sells £10,000 worth of goods and issues an invoice with 30-day payment terms. When working with an invoice finance provider, the organisation can receive an immediate advance of up to 85% of the invoice value, which in this case would be £8,500.
This money can be used to invest in new equipment, hire staff, or pursue new business opportunities.
When the customer pays the invoice after 30 days, the invoice finance provider will release the remaining 15% (£1,500 in this case) to Organisation X, minus a services charge and/or other related fees.
The fees charged by the invoice finance provider are dependent on factors such as the creditworthiness of the business and its customers, the volume of invoices being financed, and the specific terms of the invoice finance agreement.
By filling out this form, you agree to the terms laid out in our privacy policy


It is important to make you aware of all aspects of Invoice Finance so you can understand if it is the right fit for your business.
We would recommend getting in touch with Bluestone up to three months before you need an invoice finance facility for more complex cases. However, we can look to provide finance within a few weeks for simple cases.
At Bluestone, we understand that applying for a self-assessment loan can be a daunting process, especially if you're unfamiliar with the requirements and criteria. That's why we're here to support you every step of the way.
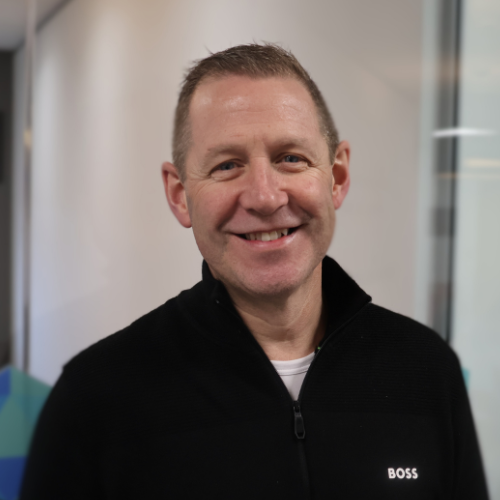
You’ll deal directly with our business loan specialist, James Lewis, who’ll support you every step of the way.
James has years of experience helping individuals like you secure the funding they need to cover their self-assessment tax bills.
He'll work closely with you to understand your specific requirements and provide you with a range of financing options tailored to your needs.
You can contact our Loans Specialist, James Lewis at james.lewis@bluestone.app.
Alternatively, visit his page to book a meeting.
If you're considering invoice finance for your organisation, the next step is to reach out to our team of experts at Bluestone.
We understand that navigating commercial finance can be a daunting process, especially if you're unfamiliar with the requirements and criteria.
Our team of finance experts have years of experience helping organisations like yours secure the funding they need. We'll work closely with you to understand your specific requirements and recommend options tailored to your business needs.
Contact us today for a no-obligation conversation about your financial requirements.

The repayment terms and conditions for invoice finance will depend on the finance provider and the specific terms of the loan. Typically, invoice finance is repaid when the customer pays the invoice, and the finance provider takes a percentage of the payment as repayment for the loan. The exact repayment terms and conditions will impact your cash flow, and we will work with you to find the best invoice finance solution to meet your specific needs and maintain positive cash flow.
BS.202311.01FAQ59
Yes, there may be fees and charges associated with invoice finance, including application fees, origination fees, and interest charges. The exact fees and charges will depend on the provider and the specific terms of the loan. We will work with you to provide an estimate of these costs and find the best invoice finance solution for your needs.
BS.202311.01FAQ7
The amount of financing that you may be eligible for through invoice finance will depend on the value of your outstanding invoices and the financial performance of your business. We will work with you to evaluate your financial situation and determine the amount of financing that you may be eligible for.
BS.202311.01FAQ39
Invoice finance is a type of financing that allows organisations to receive an advance payment on outstanding invoices. This type of financing is often used by organisations that are waiting for payment from customers, and it helps to improve their cash flow and reduce the wait time for payment. Invoice finance typically involves the organisation selling its outstanding invoices to a finance provider in exchange for an advance payment, which is typically a percentage of the invoice value. The finance provider then collects payment from the customer and the organisation repays the loan, plus fees and interest, when the customer pays the invoice.
BS.202311.01FAQ22
We know finance can be complex and often it's easier to talk things through. Drop us a message or give us a call 0330 135 8660 and we'll get back to you ASAP.

Our team are here for you, let us show you what we can do!
By filling out this form, you agree to the terms laid out in our privacy policy